


TL;DR Key Takeaways
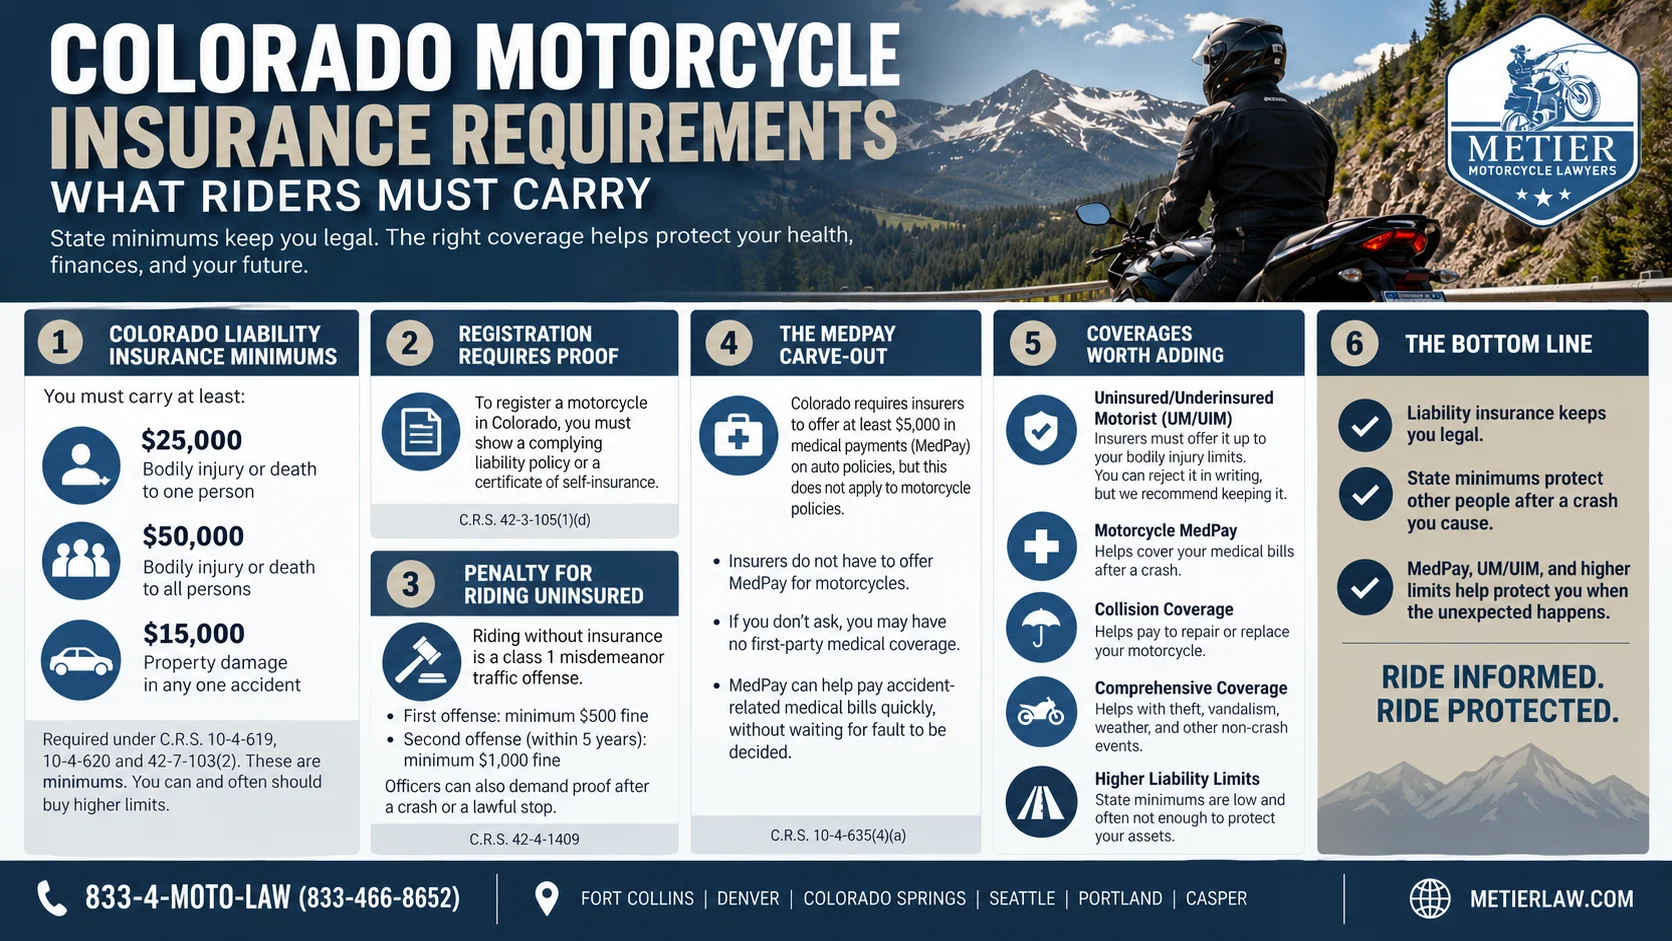
- Colorado motorcycle insurance minimums are at least $25,000/$50,000 bodily injury and $15,000 property damage on public highways.
- Registration needs proof of a complying policy. Riding without one is a class 1 misdemeanor traffic offense with a mandatory minimum fine.
- Ask for motorcycle MedPay Colorado coverage, because the auto MedPay offer rule does not apply to motorcycle policies.
- Insurers must offer UM/UIM up to your bodily injury limits, but you can reject it in writing. We recommend riders keep it.
- State minimums protect other people after a crash you cause. They do little for your bills when the other driver only carries $25,000.
When Denver and Front Range riders ask us what Colorado motorcycle insurance requirements force them to buy, they want a short checklist. The checklist exists, but what you really need to know is the harder parts that get left out. Colorado is a fault-based system, and liability pays when you injure someone else or damage their property. It doesn’t pay your own trauma care by default. At Metier Motorcycle Lawyers, motorcycle lawyer Patrick DiBenedetto and our team see this gap frequently.
As Patrick puts it: “The riders who get hurt the worst are often the ones who bought the cheapest legal policy and never asked what was missing. Liability keeps you legal. MedPay and strong UM/UIM are what keep a crash from emptying your savings.”
What Colorado Motorcycle Insurance Requirements Mandate
C.R.S. § 10-4-619 says every motor vehicle owner who drives on Colorado’s public highways, or who knowingly lets someone else do so, must keep a complying liability policy. Motorcycles fall within that rule. Colorado motorcycle liability insurance floors can be found in C.R.S. § 10-4-620 and C.R.S. § 42-7-103(2):
- $25,000 for bodily injury or death to any one person in any one accident
- $50,000 for bodily injury or death to all persons in any one accident
- $15,000 for property damage in any one accident
Those numbers are floors, not goals. C.R.S. § 10-4-621 says required coverages are minimums. You can buy higher limits, and you often should. If you are shopping for motorcycle insurance Colorado carriers offer, confirm those liability figures on your declarations page.
Colorado’s General Assembly says the same thing. Owners must carry liability insurance that pays when the insured is at fault. Current Part 6 rules do not add compulsory personal injury protection (PIP) on top of that duty.
Registration and proof of insurance
To register a Class C motor vehicle, including a motorcycle, you must show a complying policy or a certificate of self-insurance under C.R.S. § 42-3-105(1)(d). Class C covers motor vehicles that are not Class A or Class B under C.R.S. § 42-3-106(2)(c).
Penalty for riding uninsured
C.R.S. § 42-4-1409 bans driving, or letting someone drive, a motor vehicle on public highways without a complying policy. A violation is a class 1 misdemeanor traffic offense. A first offense carries a mandatory minimum fine of $500, and the court may impose more. A second conviction within five years carries a mandatory minimum fine of $1,000. Officers can also demand proof after a crash or a lawful stop.
The MedPay Carve-Out Most Riders Never Hear About
This is the gap we want every Colorado rider to understand. For many auto policies, Colorado makes insurers offer at least $5,000 in medical payments coverage. The named insured can reject it in writing under C.R.S. § 10-4-635.
That section does not apply to motorcycle policies.
C.R.S. § 10-4-635(4)(a) excludes a person buying a policy that covers a motorcycle, autocycle, low-power scooter, or toy vehicle (as defined in section 42-1-102), among other vehicles. Your insurer does not have to push MedPay onto your motorcycle policy the way it often must for a car. If nobody offers it, and you do not ask, you may have no first-party medical benefit for that ride.
Motorcycle MedPay Colorado benefits can pay accident-related medical bills fast, without waiting for fault to be decided. On a car policy, the default offer starts at $5,000. On a motorcycle policy, nothing is automatic under that statute. Ask your agent to add it in writing. Confirm the limit on your declarations page. Keep a copy of any rejection.
That carve-out is why optional coverage matters more than the legal floor. Colorado motorcycle liability insurance answers a legal checklist. MedPay helps answer the hospital bill.
Coverages Worth Adding Beyond the Legal Floor
Higher liability limits
A serious injury can use up $25,000 per person in days. Higher bodily injury and property damage limits protect your assets if you cause a crash. They also give hurt parties a fairer recovery source when fault lands on you. Colorado minimum coverage motorcycle policies meet the statute, but often leave little room after a hard impact with serious injuries.
Uninsured and underinsured motorist coverage
Under C.R.S. § 10-4-609, a Colorado motor vehicle liability policy must include uninsured motorist protection unless the named insured rejects it in writing. Before issue or renewal, the insurer must offer that protection up to your bodily injury limits. It also covers harm from an underinsured driver.
For more on UM/UIM, read our guide to uninsured and underinsured motorist insurance in Colorado. Keep it, and match it to meaningful bodily injury limits.
Collision and comprehensive
These optional physical-damage coverages are not part of the compulsory package. Whether they make sense depends on value, deductible, and financing.

When the At-Fault Driver Only Carries $25,000
Drivers who carry only the statutory minimum can still put you in the hospital after a left-turn crash. Their bodily injury limit for you may stop at $25,000. An ambulance ride, ER care, imaging, and surgery can use that amount up fast.
That is when your own UM/UIM and any MedPay you bought start paying real bills. Settlement value then turns on available coverage, injury severity, and fault. We break that down in how much a motorcycle accident settlement is worth in Colorado. Don’t take the first check from a minimum-limits carrier before you know what coverage exists on both sides.
If your own insurer stalls on benefits you paid for, see what to do when the insurer delays or denies your injury claim. Before you talk to an adjuster, review what not to say to insurance after a motorcycle accident in Denver.
Frequently Asked Questions
Is motorcycle insurance required in Colorado?
Yes. If you own a motorcycle and use it on Colorado’s public highways, or knowingly let someone else do so, you must carry a complying liability policy under C.R.S. § 10-4-619. The Colorado motorcycle insurance requirements set the minimum coverage limits at $25,000/$50,000/$15,000 under C.R.S. § 10-4-620. Riding without coverage can bring penalties under C.R.S. § 42-4-1409. Registration generally needs proof of coverage.
Does Colorado require MedPay on motorcycle policies?
No. C.R.S. § 10-4-635 forces an offer of that benefit on many auto policies, but subsection (4)(a) says the section does not apply to motorcycle policies. You can still buy it, but you usually have to ask.
Can I reject UM/UIM coverage on my motorcycle policy?
Yes, in writing. C.R.S. § 10-4-609 requires the offer and allows a written rejection. Rejecting it leaves you exposed when the at-fault driver has no insurance or only thin limits.
What happens if I am hit by a driver with only $25,000 in coverage?
Their liability insurer may pay up to that limit on your claim against their insured. Amounts above that often depend on your own UM/UIM, other policies, assets of the at-fault party, and the crash facts. Talk with counsel before you settle.
Pull Your Declarations Page Before the Next Ride
We ride these roads too. We have sat with clients who thought “I have insurance” meant “I have the right insurance.” Motorcycle insurance requirements Colorado riders need go past the compulsory package. The MedPay carve-out, thin limits, and skipped UM/UIM rejections are where riders get blindsided. A Denver motorcycle accident lawyer at Metier Law Firm can review a crash against the coverages that actually exist. When you're ready to talk through your policy or your claim, start by reaching out for a free consultation. Call Metier Motorcycle Lawyers at 833-4-MOTO-LAW (833-466-8652) or schedule your free consultation today at www.metierlaw.com.
Disclaimer: Past results discussed should not be considered a guarantee of your results as the factors of every case are individually unique. This content is for informational purposes only and does not constitute legal advice. Consult a qualified attorney from Metier Law Firm regarding your individual situation for legal advice.
Tell Us About Your Case – Free Case Review with a Personal Injury Lawyer
(866) 377-3800Our Locations

Do I have a Case?
How Much Should I Be Offered?
Do I Need an Attorney?
If these questions have crossed your mind, let us help. You may need a little direction or may not need an attorney at all, but you deserve to be confident knowing your options. We can provide you with information about our Attorneys of the West® accident investigations and legal services. Your confidential consultation with us is totally free.
Keep up with us!
